Showing posts with label XAU. Show all posts

Sunday, March 25, 2012

Negative excursion volatility based stops

Over the past few months I have begun to employ more and more traditional price based stops. The beginning of this year found meantrades reaching into drawdowns which I was not that comfortable trading with. Taking hard stops and walking away for the day is tough in any system but when applying it to a mean reversion system it means you are inevitably getting stopped out just before the market turns.

Since employing supertrend volatility metrics I realized that there is a remarkably consistent pattern occuring between price action and the ATR based indicator popularly known as supertrend. When the market reverses and the signal is created in the meantrades system very often if the market does not take off in the expected direction it will pasue for a while and then resume the expected direction. However if it doesn't it will accelerate resuming the trend creating a negative excursion for meantrades. This is ok, I have always dealt with this and will continue to do so. But the beauty of supertrend is that it allows you a chance to observe price action and its commitment for continuation or mean reversion.

So I'm adjusting my stop method slightly again. Instead of taking the swing high or low I will employ the  supertrend crossover on its second negative excursion.

You can see in the screenshot below that a signal was generated at 11:24 and then the market resumed its uptrend. Once more the market began to revert to its mean however it could not reverse as anticipated so a stop was taken on the second supertrend crossover to the upside. Notice that the stop taken is actually lower than the swing high--where we have been taking stops for the past few months.
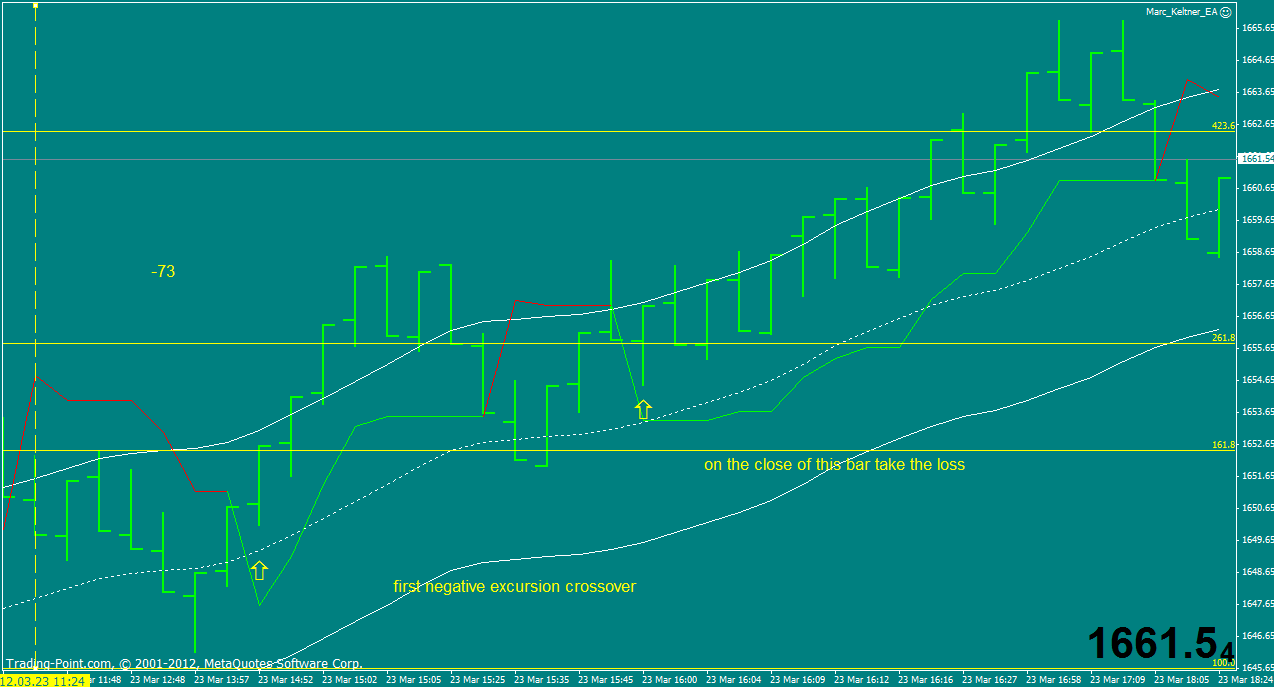


This stop method does have an unpleasant downside. You cannot know exactly where you will stop out before you enter the trade. However taking the observations of legendary traders who have come before me as dogma, it has been said time and time again, markets revert to their mean, even on a fractal level and thus for every larger stop painfully absorbed, there will be many smaller stops which create more meantrades alpha in a longer data set. Markets will always seek the most viscous point to move towards in order to damn the largest amount of traders in the market. By employing a volatility based stop which assumes markets will revert on every level of price action, stops should see a positive reduction in end of day balance draw-downs. However this means intraday account balances will almost certainly increase.

Employing this stop revision, results from the 3rd week in March have been encouraging.

EUR 3/19-3/23: +160
GBP 3/19-3/23: +47
XAU 3/19-3/23: +184 (this includes the stop posted above on Friday's trade)

Saturday, November 5, 2011

Filtering trades on XAU via time analysis

Yesterday was a really tough day on XAU. Until friday I was averaging more than 40 pips per trade on the XAU market. I decided to take a look at what was going wrong. The obvious was it was the first Friday of the month--this is usually an extremely low volume time to trade. It is often mistaken to be high volume but in fact the volatility skew on NFP days is due to a LACK of volume not a surplus of participants.

What I discovered over the past 30 days is that XAU has a very strong tendency to whipsaw at 3 intervals during the day. Note, all times are GMT +2.

The first, and perhaps most obvious was 12:00. This is when London is at lunch and NY is still in bed. Nobody should be trading signals at this time of the day. The second was the beginning of the afternoon session in London and NY is just waking up at 14:00. The consistency of the whipsaws was quite interesting. It's been common knowledge that market makers adjust prices rather violently when there is no news and their order books seem imbalanced. Best thing to do is to avoid signals which are created from this activity.

Avoiding these transitional periods in the XAU spot market added quite a return to the past performance for the last 30 days. Perhaps you too could benefit from observing what time of the day bad trades are coming in.

The other side of this coin is that the all time biggest winners will invariably come at the times most commonly creating bad trades. This is what the Black Swan theorists are always harping on about. Very low frequency returns will always outpace steady small profits. As a intraday trader, I cannot grab all of a move but I can take  what is obvious to me here and now. Once in a while I will nail those fat tail returns but it is best not to hunt for them like a hidden giant in the forest.